Contractor Insurance Explained for Homeowners Protection
Contractor insurance explained for homeowners protection: learn to verify policies and avoid liability. Call (833)-439-3727 for free contractor quotes.
By Leo Dawson
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
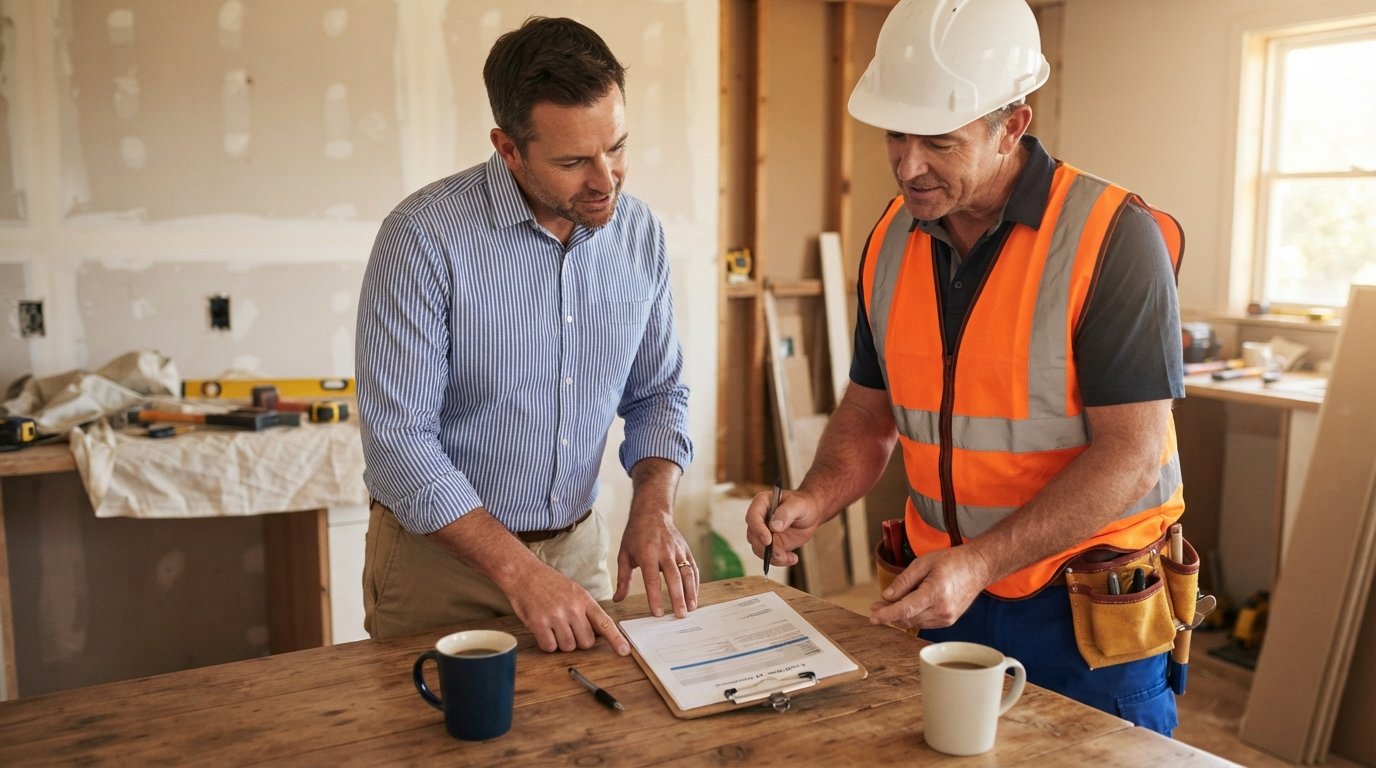
When you hire a contractor for a remodel, repair, or upgrade, you are inviting a team of workers into your home and putting your property in their hands. The quality of their work matters, but so does the safety net behind it. Contractor insurance is that safety net: it protects you from financial ruin if a worker is injured on your property or if their work damages your home. Without it, you could be held liable for medical bills, legal fees, or structural repairs that run into the tens of thousands of dollars. This guide breaks down contractor insurance explained for homeowners protection, so you know exactly what to ask for and how to verify it before work begins.
Why Contractor Insurance Matters for Homeowners
Many homeowners assume the contractor's insurance only covers the contractor. In reality, it shields you from liability. If an uninsured painter falls off a ladder and breaks an arm, your homeowner's policy might be forced to pay for their medical care. If a crew accidentally knocks out a load-bearing wall and the house shifts, you could be stuck paying for repairs if the contractor has no general liability coverage. In some states, you can even be sued by an injured worker if the contractor lacks workers compensation.
Insurance also signals professionalism. A contractor who carries proper coverage has invested in their business and is more likely to follow safety protocols. Before you sign any contract, you should request proof of insurance and verify it yourself. This simple step is one of the most effective ways to protect your home and your finances.
General Liability vs. Workers Compensation: What Each Covers
The two core policies you need to confirm are general liability insurance and workers compensation. They serve different purposes and neither replaces the other.
General liability insurance covers third-party bodily injury and property damage caused by the contractor's operations. For example, if a worker drops a hammer through your window or a subcontractor accidentally floods your basement, general liability pays for the repairs. It also covers legal defense if someone sues you or the contractor for injuries that occur on your property. Most reputable contractors carry at least $1 million per occurrence, but for larger projects you may want to ask for higher limits.
Workers compensation insurance covers medical expenses and lost wages for employees who are injured on the job. If a carpenter cuts a finger or a roofer falls from a ladder, workers comp pays for their treatment and recovery, regardless of who was at fault. This coverage also protects you from lawsuits. In most states, if a contractor has workers comp, an injured employee cannot sue you for negligence. If the contractor does not have workers comp, the injured worker might come after your homeowner's policy instead.
Here is a quick comparison to keep in mind:
- General liability: protects your property and third parties from damage or injury caused by the contractor's work.
- Workers compensation: protects the contractor's employees and shields you from liability for on-site injuries.
- Both are essential: a contractor should carry both, and you should verify both before work starts.
Some contractors also carry commercial auto insurance, which covers vehicles used for the business, and tools and equipment coverage. While these are less critical for your protection, they indicate a well-insured operation.
How to Request and Verify Certificates of Insurance
Asking for a certificate of insurance is not rude; it is standard practice. A reputable contractor will have a certificate ready to share. The certificate should list the policyholder's name (the contractor's business), the insurance company, policy numbers, coverage limits, and the effective dates. Make sure the dates cover the entire duration of your project.
Do not stop at receiving the certificate. Call the insurance company listed on the document to confirm the policy is active and the limits are accurate. Scammers have been known to alter certificates, so a quick phone call to the insurer can save you from a costly mistake. Also, check that the contractor's name on the certificate matches the name on your contract. If a subcontractor will be on site, ask for their insurance information as well.
For larger projects, you may want to request a copy of the actual policy declarations page, which provides more detail than a certificate. Keep copies of all insurance documents with your project records. If a dispute arises later, you will have proof that you exercised due diligence.
What Happens If an Uninsured Worker Gets Hurt on Your Property
This is the nightmare scenario: a worker without insurance is injured in your home. Without workers compensation, the worker may file a claim against your homeowner's policy. Your insurer might pay for medical bills and lost wages, but your premiums could rise, and your policy might not cover all costs. In severe cases, you could be sued for negligence if the injury was caused by unsafe conditions on your property.Even if you are not found liable, the legal fees and stress can be overwhelming. That is why verifying workers compensation is non-negotiable. If a contractor cannot provide proof of workers comp, consider hiring someone else. The short-term savings are not worth the long-term risk.
If you hire a sole proprietor or a handyman without employees, they may not be required to carry workers comp in some states. In that case, ask about their general liability coverage and consider requiring them to sign a waiver. However, for any project involving multiple workers or high-risk tasks (roofing, electrical, plumbing), insist on full coverage.
When to Ask for Additional Insured Status
Additional insured status is an endorsement that extends the contractor's liability coverage to include you, the homeowner. It means if a claim arises from the contractor's work, the contractor's insurance will defend you as well. This is especially important for large renovations, additions, or any project where the potential for property damage is high.
To request additional insured status, ask the contractor to add you to their policy as an additional insured. The contractor will need to contact their insurer, and there may be a small fee. You should receive a updated certificate showing your name as an additional insured. Not all contractors will offer this automatically, so you must ask. For major projects, it is a reasonable request that reputable contractors will accommodate.
Keep in mind that additional insured status does not replace your own homeowner's insurance; it simply adds an extra layer of protection. It is particularly valuable if you are acting as your own general contractor and hiring subcontractors directly.
Steps to Protect Yourself Before Hiring a Contractor
Now that you understand the insurance basics, here is a practical checklist to follow before you hire any contractor. These steps will help you avoid surprises and ensure your project is properly covered.
- Ask for certificates of insurance for general liability and workers compensation. Request them before signing a contract.
- Verify the policies by calling the insurance company. Confirm the policy numbers, coverage limits, and effective dates.
- Check that the contractor's name matches the name on the certificate and the contract.
- Request additional insured status for large projects, and get an updated certificate.
- Keep copies of all documents in your project file, including the certificate, contract, and any correspondence.
Following these steps takes less than an hour but can save you from financial disaster. If a contractor hesitates or refuses to provide insurance information, treat that as a red flag. There are plenty of qualified professionals who will gladly comply.
For more guidance on planning your project and hiring the right pro, see our article on home renovation permits explained for homeowners, which covers another critical aspect of project preparation.
Common Myths About Contractor Insurance
Many homeowners hold misconceptions about contractor insurance that can lead to costly mistakes. Here are a few myths debunked.
Myth: If the contractor has a license, they must have insurance. Licensing requirements vary by state, and not all licensed contractors are required to carry insurance. Always verify separately.
Myth: My homeowner's policy covers everything. Your policy may provide some coverage, but it is not a substitute for the contractor's insurance. Filing claims can raise your premiums and may not cover all damages.
Myth: Workers compensation only protects the worker. It also protects you from lawsuits. If a contractor lacks workers comp, you could be held liable for injuries.
Myth: Additional insured status is only for commercial projects. Homeowners can and should request it for major renovations. It is a simple way to add protection.
By understanding these myths, you can ask the right questions and make informed decisions.
How to Find Contractors with Proper Insurance
Finding a contractor who carries the right insurance starts with asking the right questions. When you request quotes, include a question about insurance in your initial inquiry. Reputable contractors will provide documentation without hesitation. You can also check online reviews and ask for references from past clients.
If you need help connecting with experienced local contractors, consider using a service that pre-screens professionals. For example, BuySellRemodel helps homeowners plan affordable home improvement projects and connect with experienced local contractors. From free estimates to remodeling, repairs, and upgrades, they make it easier to find the right pro and get the job done right. Always verify insurance yourself, even if a service claims to screen contractors.
Another tip: ask contractors if they have been sued for insurance-related issues. While they may not disclose everything, their reaction can be telling. A confident, transparent contractor will have no problem discussing their coverage.
Final Thoughts on Contractor Insurance and Homeowner Protection
Contractor insurance is not a glamorous topic, but it is one of the most important aspects of any home improvement project. By understanding the difference between general liability and workers compensation, verifying certificates, and knowing when to ask for additional insured status, you can protect your home and your finances. Remember to ask for proof of insurance before work begins, and do not be afraid to walk away if a contractor cannot provide it. Your home is your biggest investment; protect it with the same care you would expect from a professional.