Home Equity Loan Versus HELOC for a Remodel: Which Wins?
Choosing between a home equity loan versus HELOC for a remodel? Get the facts on rates and flexibility. Call 8334393727 for expert help.
By Quinn Keller
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
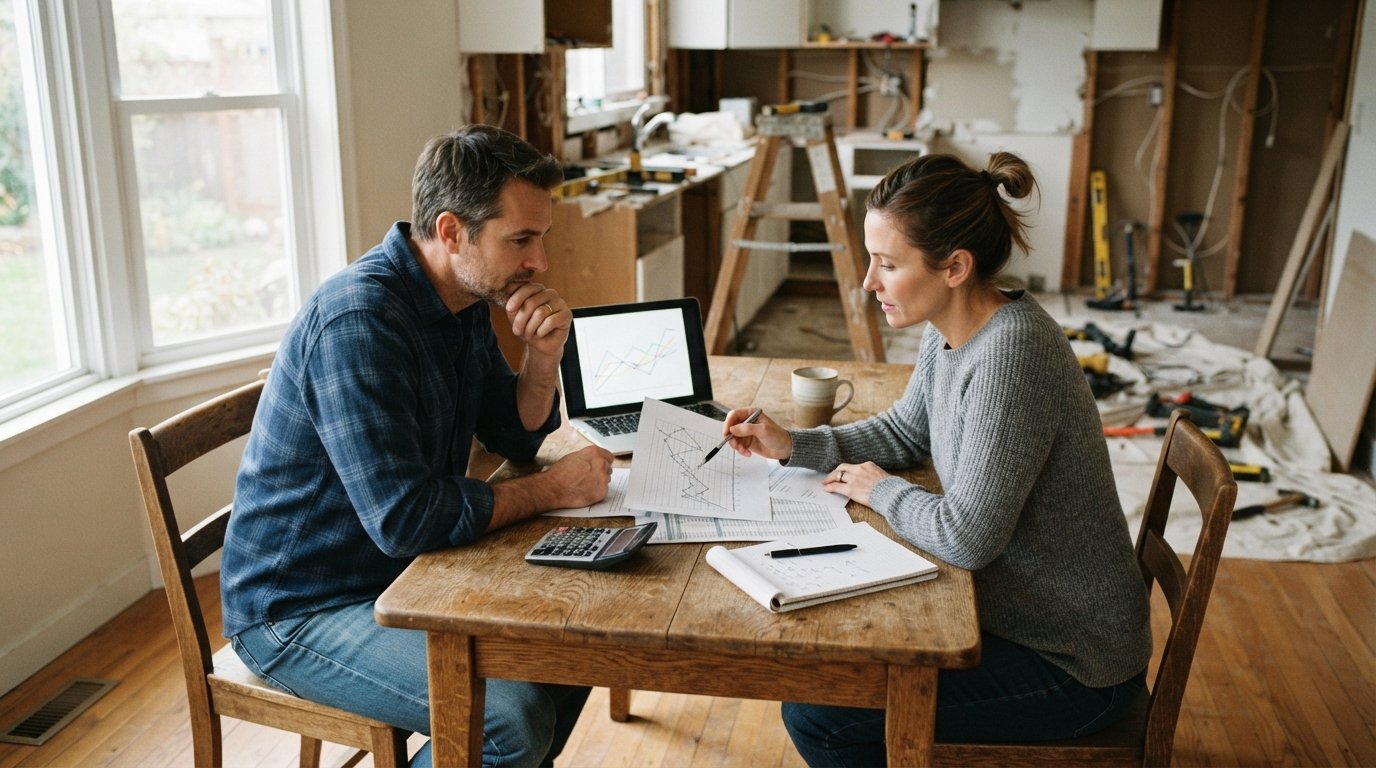
You have finally decided to pull the trigger on that kitchen overhaul or bathroom expansion, and now you are staring at the financial puzzle. Using your home's equity is often the smartest way to pay for a remodel, but the moment you start researching, you hit a wall of jargon. Home equity loan versus HELOC for a remodel is the debate that stops most homeowners in their tracks. One offers the comfort of a fixed monthly payment, while the other provides the flexibility of a credit card with a much lower interest rate. Choosing the wrong one could mean paying thousands in unnecessary interest or running out of funds halfway through demolition. This guide breaks down the mechanics, costs, and risks so you can pick the tool that matches your project timeline and budget.
How Home Equity Loans Work for Renovations
A home equity loan is essentially a second mortgage. You borrow a lump sum of money and pay it back over a fixed term, usually between five and thirty years, at a fixed interest rate. This structure makes it a favorite for homeowners who crave predictability. If you are planning a project with a known cost, like a $40,000 kitchen remodel, you know exactly what your monthly payment will be from day one until the loan is paid off.
Because the loan is secured by your home, interest rates are typically much lower than personal loans or credit cards. For homeowners who are disciplined and want to avoid the temptation of revolving credit, this is a strong option. The interest may also be tax-deductible if the funds are used to substantially improve the home, though you should always consult a tax professional regarding your specific situation.
The downside is rigidity. Once you take the lump sum, you start paying interest on the entire amount immediately, even if your contractor does not need the full payment for another three months. If your project scope changes and you need an extra $10,000, you cannot simply tap the line for more; you have to apply for a new loan or a separate credit line.
How HELOCs Offer Flexible Spending
A Home Equity Line of Credit (HELOC) works more like a credit card. You are approved for a maximum credit limit, and you can draw funds as needed, up to that limit, during a draw period that often lasts ten years. During this time, you typically only pay interest on the amount you have actually used. This makes a HELOC incredibly efficient for projects where costs are fluid or the timeline is uncertain.
If you are tackling a major renovation where you are paying subcontractors in stages (demo, framing, electrical, finishes), a HELOC allows you to borrow only what you need when you need it. This can save you a significant amount on interest charges compared to a lump-sum loan. However, most HELOCs come with a variable interest rate, meaning your monthly payment can fluctuate based on market conditions.
After the draw period ends, the loan enters repayment, where you must pay back the principal plus interest, often over a twenty-year period. This structure requires you to be disciplined. It is easy to treat a HELOC like free money and overspend on finishes or change orders. If you are not careful, you could end up maxing out the line and struggling with the repayment phase.
Comparing Costs and Interest Rates
When comparing home equity loan versus HELOC for a remodel, the math often comes down to how long you plan to hold the debt and how stable the rates are. Home equity loans usually have slightly higher interest rates than the introductory rates of a HELOC, but they are fixed. A HELOC might start with a low promotional rate, but that rate can climb significantly over time.
You also need to factor in closing costs. Many lenders offer HELOCs with no closing costs if you keep the line open for a few years, whereas home equity loans often carry application fees, appraisal fees, and origination points. Here is a quick breakdown of the cost structures:
- Home Equity Loan: Fixed rate, predictable payments, higher initial closing costs, interest paid on full amount immediately.
- HELOC: Variable rate, interest-only payments during draw period, potential for interest rate hikes, lower initial costs.
If you plan to pay off the renovation quickly (within three to five years), a HELOC with a low introductory rate might be cheaper. If you need ten years to pay it off, the stability of a fixed-rate home equity loan protects you from rising interest rates.
Impact on Your Home and Taxes
Both options use your home as collateral, which means failure to repay can result in foreclosure. This is the primary risk. However, both also offer potential tax benefits. The Tax Cuts and Jobs Act suspended the deduction for interest on home equity debt unless the funds are used to buy, build, or substantially improve the home securing the loan.
If you use the funds for a remodel, you may be able to deduct the interest. This effectively lowers the cost of borrowing. However, because the rules are complex, you should keep meticulous records of your renovation expenses. To ensure you have the documentation needed for these deductions and to avoid overpaying for the project itself, it helps to learn how to get accurate home remodeling estimates before you finalize your loan amount.
Which Option Fits Your Remodeling Timeline?
Your choice often depends on the scope and speed of your project. If you are doing a phased renovation, such as finishing a basement now and adding a bathroom next year, a HELOC is the clear winner. It allows you to keep the credit line open and use it for related projects without reapplying.
Conversely, if you are doing a single, large project with a fixed bid from a contractor, a home equity loan offers peace of mind. You know the money is in your account, and you know exactly what it costs you every month. This can make budgeting for your overall household expenses much easier.
Consider your risk tolerance as well. If a variable rate rising by two percent would strain your budget, choose the fixed-rate loan. If you are comfortable with some risk and want to minimize interest costs by paying off the debt aggressively, the HELOC provides the flexibility to do that without prepayment penalties (which are rare but should be checked).
Steps to Secure the Best Financing
Before you sign on the dotted line, you need to prepare your financial profile. Lenders typically look for a credit score of at least 620, though you will get the best rates with a score above 740. You also need to have at least 15 to 20 percent equity in your home. Here is a framework to move forward:
- Check your credit score and debt-to-income ratio to see where you stand.
- Get quotes from at least three lenders, including banks, credit unions, and online lenders.
- Compare the Annual Percentage Rate (APR), which includes fees, not just the interest rate.
- Ask specifically about closing costs, prepayment penalties, and rate caps for HELOCs.
Once you have the financing in place, the next step is finding the right professional to do the work. You do not want to borrow money only to hire a contractor who disappears halfway through the job. Connecting with experienced local contractors is essential. Platforms like BuySellRemodel help homeowners plan affordable home improvement projects and connect with experienced local contractors. From free estimates to remodeling, repairs, and upgrades, they make it easier to find the right pro and get the job done right.
Risks to Avoid with Equity Financing
Using your home as an ATM for renovations carries inherent risks. The biggest mistake homeowners make is borrowing more than the renovation adds in value. While you will enjoy the new kitchen, you do not want to be underwater on your mortgage if the market dips. Always borrow conservatively.
Another risk is the variable rate trap. If you choose a HELOC, stress-test your budget. Calculate what your payment would be if the rate increased by the maximum allowed (often capped at 18 percent or higher). If you cannot afford that payment, a home equity loan is the safer bet.
Finally, be wary of contractors who demand a large upfront payment before work begins. A reputable contractor will usually ask for a deposit (often 10 to 30 percent) but will tie subsequent payments to completion milestones.
Making the Final Decision
There is no single right answer for everyone. The home equity loan versus HELOC for a remodel decision hinges on your personal financial discipline and the specifics of your project. If you value certainty and have a fixed scope, the loan is your tool. If you need flexibility, plan to pay it off quickly, and can handle rate fluctuations, the HELOC is superior.
Whichever path you choose, ensure that the monthly payments fit comfortably within your budget. A renovation should improve your quality of life, not create financial stress. By carefully weighing the terms and planning your project thoroughly, you can use your equity to build the home you have always wanted without jeopardizing your financial future.