Best Way to Compare Financing Offers for a Home Remodel
Compare remodel financing offers with confidence by focusing on APR, fees, and total cost. Call (833)-439-3727 for free contractor estimates and expert guidance.
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
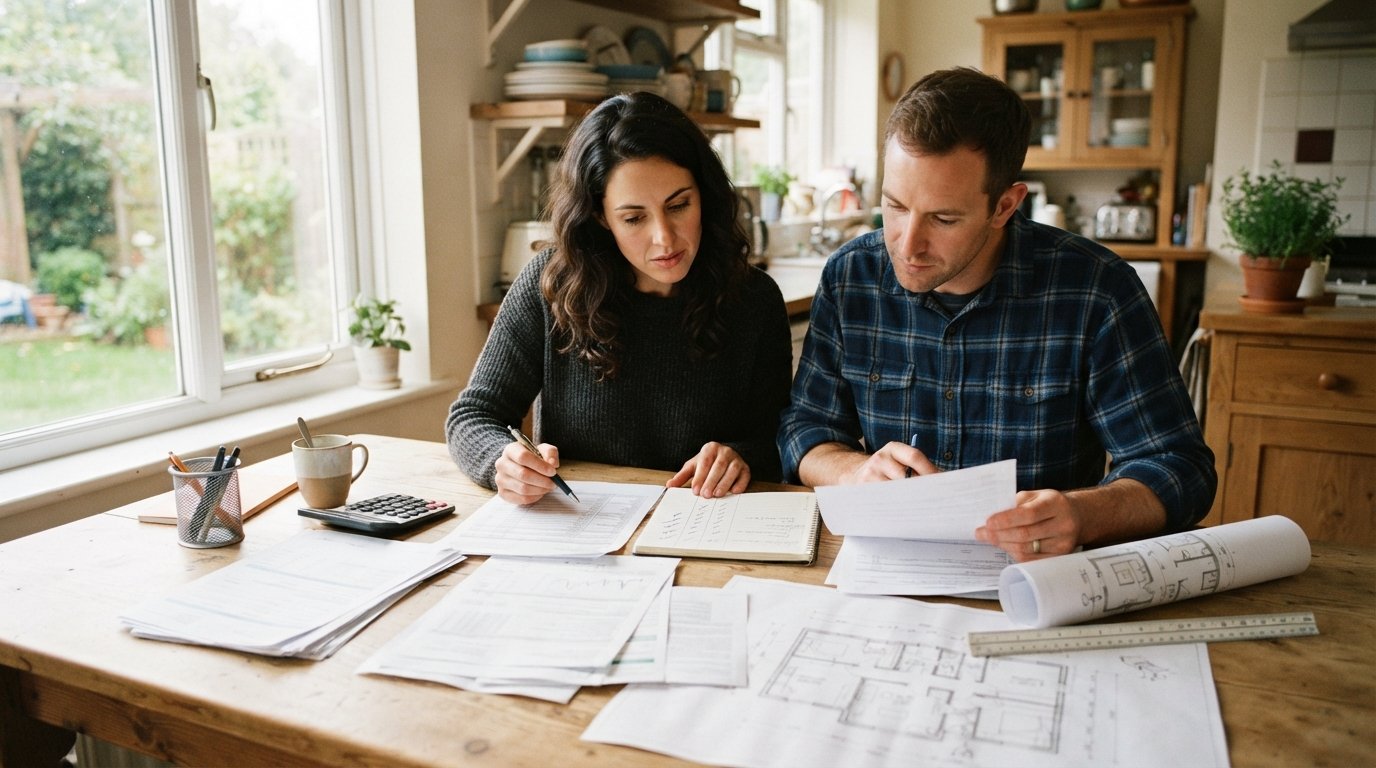
You have finally decided to remodel the kitchen, add that extra bathroom, or finish the basement. The contractor estimates are rolling in, and the numbers are bigger than you hoped. Before you sign anything, the financing offers start arriving: a home equity line, a personal loan, a contractor's in-house plan, maybe even a promotional credit card. They all look similar on the surface, but the differences in fees, rates, and repayment terms can add thousands of dollars to your project. The best way to compare financing offers for a home remodel is to move beyond the monthly payment and evaluate the total cost of borrowing, the flexibility of the terms, and the risks buried in the fine print. This guide walks you through a practical framework that homeowners can use to line up offers side by side and choose the one that truly fits their budget and long-term goals.
Start With the Total Project Cost, Not Just the Loan Amount
Before you can compare financing offers, you need a realistic picture of what the remodel will cost. Lenders will ask for a project estimate, and the amount you borrow should be based on a detailed scope of work, not a rough guess. If you are still gathering bids, start by requesting free estimates from local contractors so you know the true range of costs for your project. A contractor who specializes in your type of remodel can break down materials, labor, permits, and contingency, which gives you a solid number to bring to lenders.
Once you have a reliable project cost, add a buffer of 10 to 20 percent for unexpected issues. Remodels often uncover hidden problems like outdated wiring or water damage, and financing a little extra upfront is cheaper than scrambling for additional funds mid-project. Your loan amount should cover the full expected cost plus that cushion, so you are not forced to borrow again at a higher rate later.
With that number in hand, you can start comparing offers. But remember: the loan amount is only one piece of the puzzle. The interest rate, fees, and repayment term determine how much you actually pay over time. A lower monthly payment might mean a longer term and thousands more in interest. That is why the next step is to look at the annual percentage rate (APR), which bundles the interest rate with most fees into a single number.
Compare APR, Fees, and Repayment Terms Side by Side
The APR is the most reliable single metric for comparing loans because it reflects the true cost of borrowing, including origination fees, closing costs, and other charges. A loan with a 6 percent interest rate and no fees might have an APR of 6 percent, while a loan with a 5.5 percent rate and $2,000 in fees could have an APR of 6.8 percent. Always ask for the APR in writing and use it as your primary comparison tool.
Fees can vary widely by lender and loan type. Common fees include origination fees (often 1 to 5 percent of the loan amount), application fees, appraisal fees, and prepayment penalties. Some home equity loans come with closing costs similar to a first mortgage, while personal loans may have no fees but a higher rate. Contractor-arranged financing might advertise no fees but build costs into the rate or the project price. You need to add up every fee and compare the total cost of credit, not just the interest rate.
Repayment terms also matter. A shorter term means higher monthly payments but less interest overall. A longer term lowers the monthly burden but increases the total interest paid. Here is a simple framework to compare terms:
- Monthly payment: Can you comfortably afford it if your income dips or an emergency arises?
- Total interest paid: Multiply the monthly payment by the number of payments, then subtract the loan amount.
- Prepayment flexibility: Can you pay off the loan early without penalty? This matters if you expect a bonus or tax refund.
- Variable vs. fixed rate: A variable rate may start lower but rise over time. Fixed rates offer predictability.
Use a spreadsheet or an online loan calculator to run these numbers for each offer. Seeing the total interest cost next to the monthly payment often makes the trade-offs obvious. A 10-year loan at 7 percent might cost $4,000 less in total interest than a 15-year loan at 6.5 percent, even though the monthly payment is higher. Only you can decide which balance works for your budget, but the comparison should be based on full numbers, not just the teaser rate.
Put Home Equity, Personal Loans, and Contractor Financing Side by Side
Homeowners typically have three main financing paths for a remodel: home equity products (loans or lines of credit), unsecured personal loans, and contractor-arranged financing. Each has distinct advantages and drawbacks, and the right choice depends on your equity, credit, and risk tolerance.
Home equity loans and HELOCs use your home as collateral, which usually means lower interest rates and longer repayment terms. A home equity loan gives you a lump sum with a fixed rate, while a HELOC works like a credit card with a variable rate and a draw period. These options are attractive if you have substantial equity and can qualify, but they put your home at risk if you default. Closing costs can also be significant, so they make the most sense for larger projects where the lower rate offsets the fees.
Personal loans are unsecured, meaning they do not use your home as collateral. They come with fixed rates and terms, and approval can be fast. However, interest rates are typically higher than home equity products, especially for borrowers with less-than-perfect credit. Personal loans work well for smaller remodels or when you want to avoid putting your home on the line. Compare the APR carefully, as origination fees can vary widely.
Contractor-arranged financing is offered through the remodeling company, often via a third-party lender. These plans can be convenient and may include promotional rates like 0 percent for 12 months. But read the fine print: deferred interest promotions can retroactively charge high interest if you do not pay off the balance within the promotional period. Contractor financing may also have higher rates than you could get on your own, and some contractors mark up the project price to cover financing costs. Always ask for the financing terms in writing and compare them to your other offers.
To make an apples-to-apples comparison, create a simple table with columns for APR, fees, monthly payment, total interest, and risk (secured vs. unsecured). Then rank each offer based on what matters most to you: lowest total cost, lowest monthly payment, or fastest approval. For a deeper dive into loan types and how to choose among them, see our guide on smart financing options for home improvement projects.
Calculate How Interest Costs Change the Total Project Price
A remodel financed over time costs more than the sticker price. The interest you pay is part of the project cost, and even a small difference in APR can add up. For example, borrowing $30,000 at 7 percent over 10 years costs about $11,700 in interest, bringing the total to $41,700. At 9 percent, the interest jumps to about $15,600, for a total of $45,600. That $3,900 difference could pay for new appliances or a significant portion of the labor.
To see the real impact, run the numbers for each offer using the loan amount, APR, and term. Then ask yourself: is the lower monthly payment worth the extra interest? Sometimes stretching the term makes sense to keep cash flow stable, but you should make that choice consciously. Also consider the opportunity cost: money spent on interest cannot be invested or used for other home improvements.
Another factor is the tax treatment of interest. Interest on home equity loans and HELOCs may be tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. Personal loan interest is generally not deductible. Consult a tax professional for your situation, but this can tip the scale toward home equity products for large remodels.
Finally, think about the total cost of the project including financing. If you are comparing contractors, a bid that seems $2,000 higher but comes with lower-cost financing might actually be cheaper overall. Always compare the all-in cost: project price plus financing charges.
Ask These Questions Before Signing Any Financing Offer
Financing offers can be complex, and the details matter. Before you commit, ask each lender the following questions and get the answers in writing:
- What is the APR, and what fees are included in it?
- Is the rate fixed or variable? If variable, how often can it change and what is the cap?
- Are there prepayment penalties or fees for paying off the loan early?
- What happens if I miss a payment or default? What are the late fees and consequences?
- For contractor financing, is the rate promotional? What happens after the promotional period ends?
Red flags include pressure to sign immediately, vague answers about fees, promises of "no interest" without clear terms, and lenders who discourage you from comparing offers. A reputable lender will encourage you to take your time and will provide a clear loan estimate or truth-in-lending disclosure. If something feels off, walk away.
Also verify the lender's reputation. Check reviews with the Better Business Bureau and state licensing boards. For contractor-arranged financing, confirm that the contractor is licensed and insured, and ask whether they receive a commission from the lender. Transparency is a good sign.
Timing Matters: Get Financing Approval Before Requesting Contractor Estimates
Many homeowners make the mistake of shopping for contractors first and financing later. This can lead to disappointment if the loan amount falls short, or it can pressure you into a rushed decision. Instead, get pre-approved for financing before you request estimates. Pre-approval gives you a clear budget and signals to contractors that you are a serious buyer. It also lets you compare contractor bids with confidence, knowing exactly how much you can afford.
Pre-approval is not a final commitment, but it involves a credit check and documentation of income and assets. It typically lasts 60 to 90 days, so time your pre-approval to coincide with your contractor search. With a pre-approval letter in hand, you can ask contractors for detailed proposals that fit your budget, and you can negotiate from a position of strength.
If you need help finding reputable contractors in your area, BuySellRemodel connects homeowners with local professionals for free estimates and project planning. Their service can simplify the process of gathering bids and comparing options, so you can focus on choosing the right financing. Remember, the best way to compare financing offers for a home remodel is to have your project numbers and loan pre-approval ready before you start negotiating with contractors.
Once you have pre-approval and contractor bids, you can finalize your loan choice. Review the offers side by side one last time, confirm the APR and fees, and make sure the monthly payment fits comfortably in your budget. Then sign with confidence, knowing you have compared the true cost of each option.
Putting It All Together: A Step-by-Step Comparison Process
Here is a recap of the process in five steps:
- Get detailed contractor estimates and add a 10 to 20 percent contingency.
- Gather financing offers from at least three lenders, including home equity, personal loans, and contractor financing.
- Compare APR, total fees, monthly payment, and total interest using a spreadsheet or loan calculator.
- Ask the questions above and watch for red flags.
- Get pre-approved before finalizing contractor bids, then choose the offer with the best overall fit for your budget and risk tolerance.
By following this framework, you can avoid the common pitfalls of remodel financing: paying too much in interest, getting stuck with a loan that strains your budget, or discovering hidden fees after the project is underway. The best way to compare financing offers for a home remodel is to be thorough, ask questions, and look at the total cost rather than the monthly payment alone.
Remodeling your home is a big investment, but the right financing can make it manageable. Take the time to compare offers carefully, and do not be afraid to negotiate or walk away from a bad deal. With a clear plan and a bit of homework, you can fund your remodel without compromising your financial health.