Large Contractor Deposit? What to Do Before You Pay
A contractor asking for a big upfront deposit? Learn how to verify, negotiate, and protect your money. Call (833)-439-3727 for local contractor guidance.
By Sarah Thomas
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
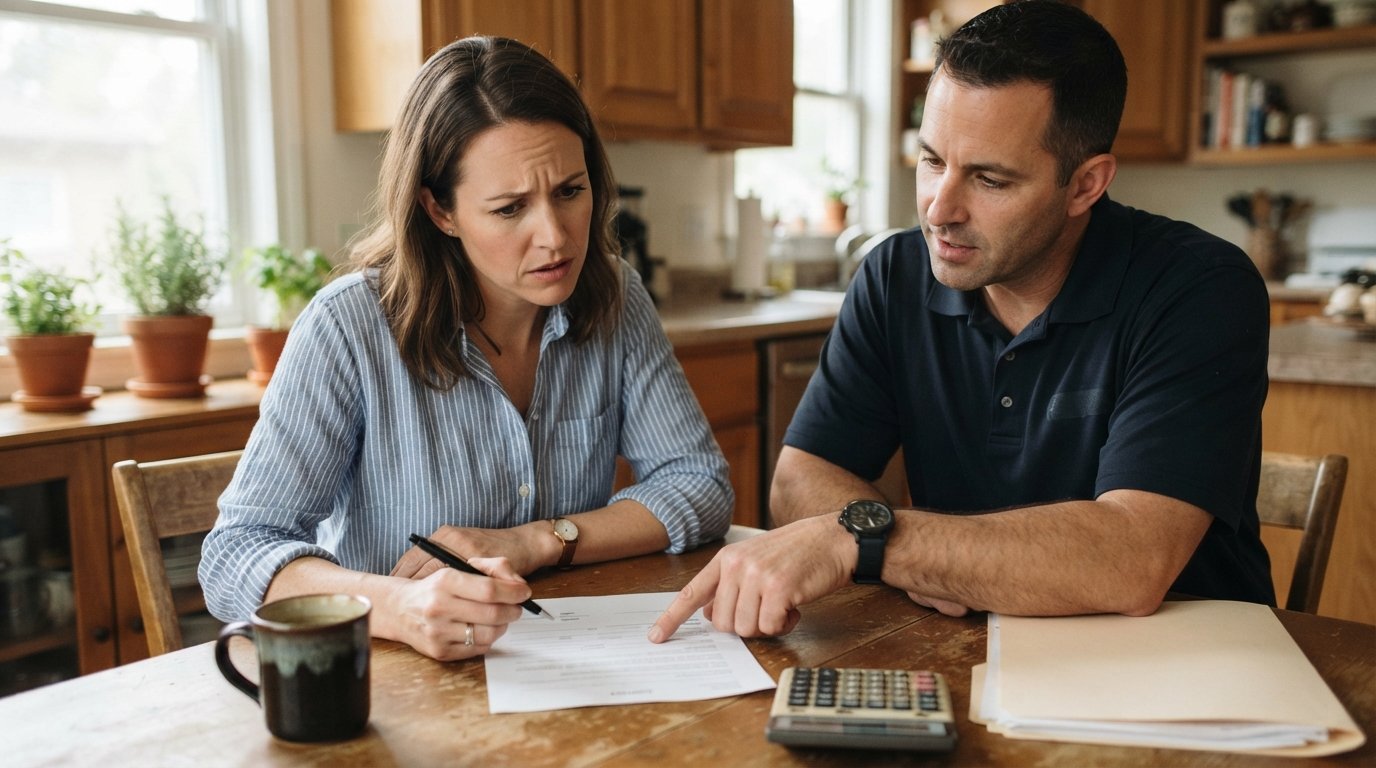
Your contractor just handed you a contract with a line that makes your stomach drop: a request for 50 percent of the project cost upfront, in cash, before a single shovel hits the dirt. You want the work done, but something feels off. Should you pay it and hope for the best, or is this the moment to pump the brakes? The answer depends on a few key factors, and knowing how to read them can save you thousands of dollars and months of frustration.
Large upfront deposit requests are one of the most common pressure points in home improvement projects. They can be perfectly legitimate, especially when custom materials or special-order items are involved. But they can also be the first warning sign of a contractor who is undercapitalized, overbooked, or worse. This guide walks you through exactly what to do if your contractor asks for a large deposit upfront, from verifying typical ranges to negotiating a safer payment schedule and knowing when to walk away.
Understand Typical Deposit Ranges and Why They Exist
Most reputable contractors ask for a deposit, and that is not inherently a red flag. A deposit protects the contractor from ordering materials or reserving crew time for a homeowner who might back out. It also covers the initial costs of permits, dumpsters, and specialty items that cannot be returned. The key is whether the amount requested falls within a reasonable range for the type of project you are planning.
For most residential remodeling and repair projects, a deposit of 10 to 30 percent of the total contract price is standard. Smaller repair jobs might require a flat fee or a one-third deposit. Larger projects with significant custom material orders, such as kitchen cabinets, custom windows, or specialty tile, sometimes justify deposits at the higher end of that range because the contractor is fronting real money to suppliers. The table below gives a general sense of how deposit expectations vary by project type, though local norms and individual contractor policies always apply.
- Small repairs and handyman work: Often no deposit or a flat fee under $500, with payment due upon completion.
- Standard remodeling (bathrooms, flooring, painting): Typically 10 to 20 percent upfront, with the balance tied to milestones.
- Projects with custom or special-order materials: 20 to 30 percent is common, sometimes with a separate materials deposit.
- Large additions or whole-home renovations: 10 to 20 percent is typical, but the payment schedule should be broken into multiple milestone payments.
If your contractor is asking for 40, 50, or even 60 percent before work begins, that is outside the normal range for most projects. It does not automatically mean fraud, but it does mean you need to ask questions and understand exactly what that money covers. A contractor who cannot explain the breakdown of the deposit in clear terms is a contractor you should approach with caution.
Why Unusually Large Cash Deposits Signal Risk
When a contractor asks for a large deposit in cash specifically, the risk profile changes significantly. Cash leaves no paper trail, offers no chargeback protection, and cannot be disputed through a credit card company or bank. Legitimate contractors generally prefer checks, electronic transfers, or credit card payments because those methods protect both parties and create a record for tax and accounting purposes. A demand for cash is one of the clearest warning signs in the contracting world.
Beyond the payment method, an unusually large deposit request can signal underlying financial instability. A contractor who needs 50 percent upfront to start your job may be using your deposit to fund a previous project, cover payroll, or pay off suppliers. This creates a dangerous cycle where your project becomes dependent on the next homeowner's deposit. If that next deposit does not come through, your project stalls, and your money is already spent. In the worst cases, homeowners have lost tens of thousands of dollars to contractors who collected large deposits and disappeared.
There is also the issue of leverage. Once you have paid a large percentage upfront, you have little control over the pace or quality of the work. The contractor has your money, and your only recourse is legal action, which is slow and expensive. A fair payment schedule keeps the contractor motivated to finish because the final payments are still on the table. A large upfront deposit removes that motivation.
Verify the Contractor Before You Hand Over Any Money
Before you negotiate anything, take a step back and verify who you are dealing with. This is the single most important thing to do if your contractor asks for a large deposit upfront. A legitimate, established contractor will have no problem providing documentation and references. If any of the following checks raise concerns, that is your signal to slow down or walk away.
- Check the license. Most states require contractors to be licensed, and you can verify status through your state or local licensing board. Ask for the license number and confirm it is active and in good standing.
- Request a certificate of insurance. The contractor should carry general liability insurance and workers compensation coverage. Call the insurance company directly to confirm the policy is current.
- Ask for local references. Request three to five references from projects completed in the past year, and actually call them. Ask about the contractor's communication, timeliness, and how they handled any problems.
- Look up complaints and reviews. Check the Better Business Bureau, your state attorney general's office, and online review platforms. A pattern of unresolved complaints is a serious red flag.
- Verify a physical business address. A contractor who operates only from a cell phone and a post office box is harder to hold accountable. A real office or shop address is a positive sign.
These checks take an hour or two, and they are worth every minute. If a contractor becomes defensive or evasive when you ask for license and insurance information, that reaction tells you something important. Professionals expect to be asked, and they provide the information readily. You can also use a service like BuySellRemodel to explore local contractor options and compare estimates before committing to a large deposit.
Negotiate a Payment Schedule Tied to Completed Milestones
If you want to move forward with the contractor but the deposit request feels too high, the best response is to propose a milestone-based payment schedule. This is a standard approach in the construction industry, and most reputable contractors will accept it. The idea is simple: you pay for work as it is completed, not before. This protects your cash flow and keeps the contractor accountable.
A fair payment schedule might look like this: a modest deposit to cover initial materials and mobilization, followed by payments at defined milestones such as demolition completion, rough-in inspections passed, drywall hung and finished, and final walkthrough. The final payment, typically 10 to 15 percent, should always be held until the job is fully complete and you have inspected the work. Here is a sample structure for a mid-sized remodeling project.
- Deposit (10 percent): Due at contract signing to cover initial material orders and scheduling.
- Milestone 1 (25 percent): Due after demolition and rough framing are complete.
- Milestone 2 (25 percent): Due after mechanical, electrical, and plumbing rough-ins pass inspection.
- Milestone 3 (25 percent): Due after drywall, paint, and major installations are finished.
- Final payment (15 percent): Due after final walkthrough, punch list completion, and your written approval.
When you propose this kind of schedule, watch how the contractor responds. A professional will negotiate in good faith, perhaps adjusting percentages to reflect material costs. A contractor who insists on a large lump sum upfront with no flexibility is showing you that their business model depends on your money, not their work. That is a risk you do not need to take.
Get Every Deposit Term in Writing
Verbal promises mean nothing when a dispute arises. If you agree to any deposit, make sure the contract spells out exactly what that money covers, when it is due, and under what circumstances it can be refunded. A well-written contract protects both parties and eliminates ambiguity. Before you sign, read the deposit and payment sections carefully, and do not be afraid to ask for changes.
The contract should specify the total project price, the deposit amount and payment method, the milestone schedule with specific dates or completion criteria, and the conditions for refunds or adjustments. It should also include a clear description of the work, the materials to be used, and the timeline for completion. If the contractor provides a contract that is vague or missing these details, ask for a revised version. You can also have an attorney review the contract before signing, especially for large projects.
Pay attention to cancellation clauses as well. If you cancel the project after paying a deposit, what happens to your money? Some contracts allow the contractor to keep the entire deposit regardless of whether any work was performed, which is unreasonable. A fair clause ties any retained amount to actual costs incurred, such as materials already ordered or permits already pulled. Understanding these terms upfront prevents ugly surprises later.
Communication is the foundation of a good contractor relationship, and that starts before the first payment. For more guidance on keeping the lines open throughout your project, see our article on how to communicate effectively with your contractor. Clear expectations about money, timelines, and changes will save you countless headaches.
Know When to Walk Away and Request Fresh Estimates
Sometimes the right answer is no. If your contractor refuses to provide a written contract, demands cash with no receipt, cannot produce a license or insurance certificate, or insists on a deposit above 30 percent with no justification, walk away. There are plenty of qualified contractors in your area who will work with reasonable terms. The temporary inconvenience of finding someone new is far better than the financial and emotional cost of a failed project.
Walking away also gives you leverage. When you request fresh estimates from multiple contractors, you can compare deposit requests, payment schedules, and contract terms side by side. You will quickly learn what is normal in your local market and which contractors are outliers. Getting three written estimates is a standard practice for any significant home improvement project, and it costs you nothing but time.
When you request new estimates, be upfront about your payment expectations. Tell each contractor that you are looking for a milestone-based schedule with a deposit in the 10 to 20 percent range. The contractors who agree without hesitation are the ones who run professional operations. The ones who push back or try to pressure you into a large upfront payment are showing you their true colors before any work begins.
Remember that the goal is not to avoid deposits entirely. A reasonable deposit is a normal part of doing business and helps ensure your project gets the attention it deserves. The goal is to protect yourself from unreasonable risk while building a fair working relationship with a contractor you trust. If you approach the conversation with clear expectations and a willingness to negotiate, you will usually find a path forward that works for both sides.
The next time a contractor asks for a large deposit upfront, you will know exactly what to do: verify credentials, ask for a breakdown, propose a milestone schedule, get everything in writing, and be prepared to walk away if the terms do not pass the smell test. Your home is likely your largest investment, and protecting it starts with protecting your wallet.